Square Freezes Verified Business Account Without Providing Any Explanation
A marketing firm submitted all required IRS and bank documents to Square, only to face an unexplained suspension and a denied appeal that ignored the company’s own service deadlines.
By Alina Marshall ·
A small online business that specializes in marketing and search engine optimization for other companies followed every protocol. The firm provided government identification for the account holder. It linked a valid checking account and submitted the Employer Identification Number document directly from the Internal Revenue Service. It used third party software to connect the banking details securely to the Square account. It produced the official LLC formation papers. It held a signed contract from a client for the full amount of the transaction.
Square suspended the account anyway.
The suspension was not triggered by a missing file. It was not caused by a failed bank verification. The IRS did not flag the EIN as invalid. Instead, Square cited a rule that did not appear on its own list of suspension reasons. The business did not break a specific regulation. The regulation itself was not formally defined. The automated system made its decision, and the system does not accept questions.
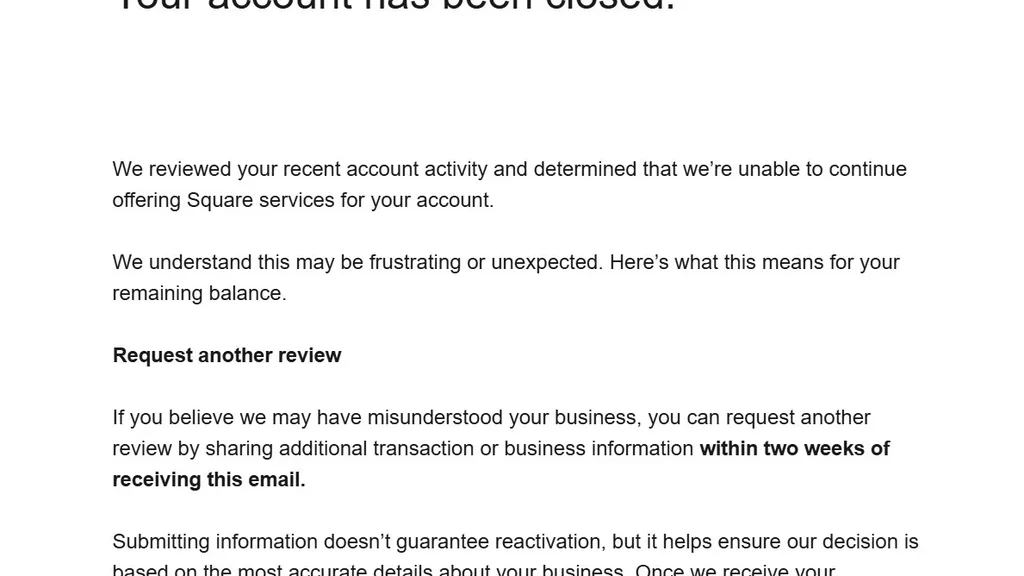
The business filed an appeal. Square promised a response within ten days. It took two weeks. When the response finally arrived, it was a denial. There was no written explanation. There was no reason listed. There was no human representative to call. There was no office to visit. There was no face to look at while someone explained why the company’s money and operations were no longer welcome.
The result was a simple denial from a machine.
The business gave Square its identity. It gave the company its tax documents. It shared its bank account details. It provided the contract proving the transaction was real and the client was legitimate. In return, the business received a suspension without a stated cause and an appeal without a clear rationale.
The most frustrating aspect of this situation is written in Square’s own contract. The company’s General Terms of Service, specifically Section 12, state that Square may terminate the terms or suspend the account at any time for any reason. The reason is effectively optional. The company can choose to act at its own discretion without providing a specific justification to the merchant.
Section 13 of the same document, titled Effect of Termination, adds another layer of protection for the company. It states that Square will not be liable to the merchant or any third party for compensation, reimbursement, or damages resulting from a termination or suspension of services. The company can hold the funds and disrupt the business operations without facing financial liability for the inconvenience or loss.
The Payment Terms add further restrictions. Section 12 of those terms allows Square to defer payout or restrict access to proceeds, either temporarily or indefinitely. This means the money a client has already paid can sit in a company account while the automated system determines the fate of the merchant. The revenue is tied up in a digital limbo.
Section 14 of the Payment Terms addresses the Reserve for Holding Funds. It states that Square may require a reserve for any reason related to the use of the services. The amount of the reserve is determined by Square, described as reasonably determined by us. It is not determined by a bank. It is not set by a regulator. It is not decided by a judge. It is set by the software company itself.
A notable contradiction appears in Section 1 of the Payment Terms. The section opens with a clear statement: We are not a bank. Square describes itself as a payment facilitator. It is a processing company. It is a software as a service platform that handles the payment and moves the money. It functions as the conduit, not the reservoir. Yet this conduit holds more power over a small business than the bank that actually holds the funds. Traditional banks must follow specific rules. They must explain their decisions. They can be regulated by federal and state authorities. Square is a software company with a suspension button, and that button seems to have no off switch.
When a merchant tries to fight a suspension, the contract is waiting. Section 22 of the General Terms prohibits class actions and jury trials. It requires individual arbitration in Oakland, California. Section 19 caps the company’s total liability to the merchant. The cap is the fees Square earned from the merchant in the three months before the problem, or $500, whichever is greater. Five hundred dollars is the maximum value of the business according to the contract.
Section 7 states that if there is a dispute about who owns the account, Square will be the sole arbiter of such dispute in its sole discretion. The decision is final and binding on all parties. The company acts as the player, the referee, and the stadium.
This is the environment that has developed around digital payments. A company that is not a bank acts like one. An automation system scrutinizes a business with zero stated reason and zero explanation. A merchant who completed every verification step is suspended by a rule that was not even a listed reason for suspension. The appeal took twice as long as promised and ended without a word.
The business cannot easily dispute the decision. To dispute it is to enter arbitration in the company’s chosen city, under the company’s rules, for a prize capped at five hundred dollars. Square even maintains a list of Unsupported Industries in its Payment Terms. Item 6 on that list is direct marketing or subscription offers or services. A marketing and SEO firm is one algorithmic decision away from that category. The machine does not need the rule to be strictly true. It needs the rule to be convenient.
Where is the bank that has to explain itself? Where is the regulator that has to show its work? Where is the human being who has to look a merchant in the eye and say we suspended you, and here is why? There is no one. There is a dashboard. There is a denial. There is a machine that has never met the business, never read the contract, and never spoken to the client, yet it has already decided.
This is not just a payment processor. It is a toll booth on the only road a small business has. The booth is run by a company that is not a bank. It is governed by a contract that says the company can do what it wants, when it wants, for any reason, and owe nothing for it.
The verified business did everything right. Square did not need it to. That is the whole story. That is the whole system. Until a company that is not a bank starts acting like one, every small business in the country is one algorithm away from losing its money, its account, and its voice. The process offers no reason given and no explanation owed.
The merchant provided the ID, the EIN, the LLC documents, and the signed contract. The bank account was verified. The client was real. The money was real. And yet the account was suspended. The appeal was denied. The deadline was missed. The explanation was never sent. The business is left with a dashboard and a denial. It is left with a contract that caps its value at five hundred dollars. It is left with a machine that does not need to justify its actions.
The terms are clear. The company may suspend the account at any time. The company may defer the payout indefinitely. The company may require a reserve for any reason. The company is the sole arbiter of disputes. The company is not liable for damages. The company is not a bank. The company is a software platform. And the platform has decided.
The business owner is left to wonder why the machine chose that moment to stop the flow of funds. The machine does not care about the marketing strategy. The machine does not care about the SEO work. The machine does not care about the client relationship. The machine only cares about the data points. And in this case, the data points triggered a suspension.
The appeal process was supposed to provide clarity. It provided a delay. It provided a denial. It did not provide a reason. The promise of a ten day response was extended to fourteen days. The result was the same. No change. No explanation. No human contact.
The contract protects the company. It limits liability. It chooses the location for arbitration. It defines the reserve. It allows for suspension without cause. It is a comprehensive document. It is a shield. And it is available on the company website for anyone to read.
The small business followed the rules. It verified its identity. It linked its bank. It submitted its tax ID. It signed the client contract. It did everything the system asked for. And the system still said no. The no came with no reason. The no came with no explanation. The no came from a machine that does not have to explain itself.
More Business · Watch Your Wallet · Report a business · Got a Story?